01 · Protection
Term Life Insurance
The most coverage for the least money, for the years your family is most exposed.
- Affordable coverage
- Income replacement protection
- Mortgage and family security
Protect what matters most
Read more about Term Life
Independent life insurance and wealth strategy for families who want more than a policy — they want a plan their children will inherit.
No obligation · No medical exam options available · No pressure
Our solutions
Four ways to protect income, build cash value, and leave money behind on purpose rather than by accident.
01 · Protection
The most coverage for the least money, for the years your family is most exposed.
Protect what matters most
Read more about Term Life02 · Growth
Protection that also builds a pot you can borrow against while you are still alive.
Grow wealth tax-advantaged
Read more about Indexed Universal Life03 · Permanence
A fixed premium and a guaranteed payout that never expires and never reprices.
Lifetime protection, lasting value
Read more about Whole Life04 · Dignity
A small, easy-to-qualify-for policy so a funeral never becomes a family debt.
Peace of mind for your loved ones
Read more about Final ExpenseSolutions for every stage of life
A policy that is right at thirty is rarely the one you want at sixty. Franca starts by working out which of these you are, then narrows to the one or two products that actually fit — rather than selling you the same plan she sold the last person who called.
Ages 25–55
Income protection, mortgage protection, and building something for the children.
Term Life · IUL
“Protect your family's future for less than the cost of your daily coffee.”
Ages 25–65
Wealth accumulation, tax-advantaged growth, and legacy planning.
IUL · Whole Life
“Build protection and long-term financial security with a strategy designed for your future.”
Ages 50–75
Final expenses, legacy planning, and leaving money to loved ones.
Final Expense · Whole Life
“Give your family peace of mind and avoid leaving them with unexpected costs.”
Before you book
No pitch attached. Each one answers in its first sentences and says who the product does not suit.
A common starting point is ten to twelve times your annual income, but that rule ignores what you owe and who depends on you. A more honest figure is the total of what would still need paying if your income stopped — the mortgage, other debts, the years of income your household would lose, and anything you intend to leave behind — minus what you already have in cover and savings.
Read the full answer · 5 min
Term life covers you for a fixed number of years and pays out only if you die within that window; it costs less because most policies never pay a claim. Whole life covers you for life and builds cash value, which is why it costs considerably more for the same death benefit. Term suits a temporary obligation like a mortgage or raising children; whole life suits a permanent one like final expenses or leaving money behind.
Read the full answer · 6 min
Indexed universal life is permanent cover whose cash value grows based on the movement of a market index, with a floor that protects against index losses and a cap that limits gains. It suits people who have already filled their tax-advantaged retirement accounts and want permanent cover with a growth component. It is a poor fit for anybody whose priority is the largest possible death benefit for the lowest premium.
Read the full answer · 7 min
FaithFinanceFreedom
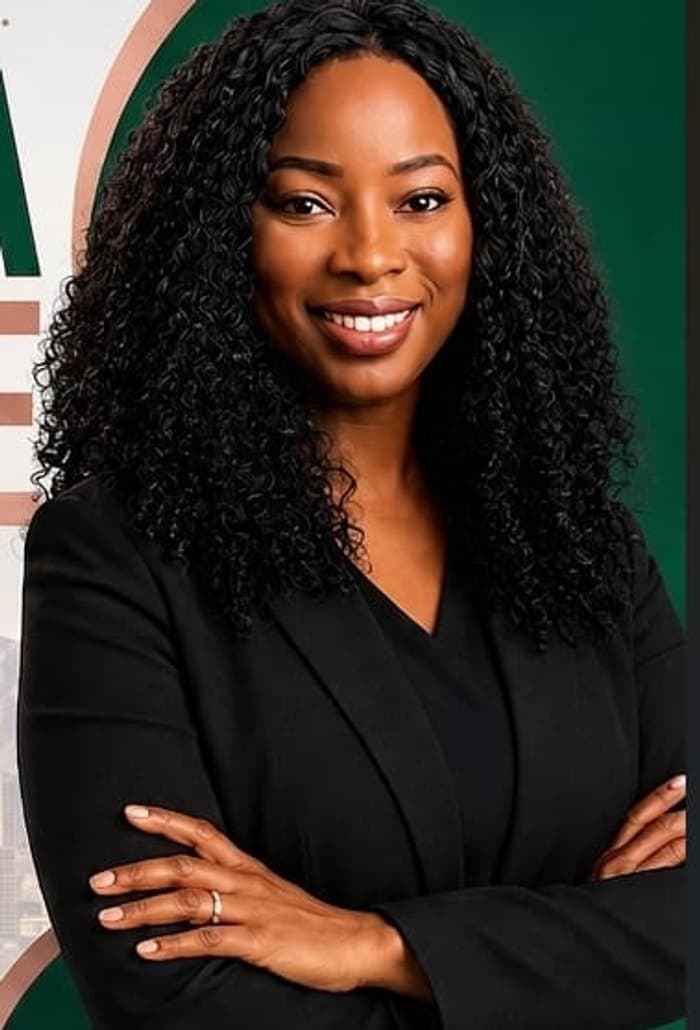
Meet your advisor
Ambassador Franca Adetunji · Licensed Financial Professional · Wealth Strategist · Mentor
Franca helps families build wealth, protect income, and create lasting legacies. As an independent professional she is not tied to a single carrier’s shelf — which means the recommendation starts with your situation, not with a quota.
There is also something I won't do: I won't pressure someone into buying a financial product they don't understand or that isn't appropriate for their situation. I believe you deserve to know what you're paying for, how it works, what the benefits are, what the limitations are, and what alternatives you may have. BrightCover isn't about algorithms making decisions for people. It's about having a real, licensed professional you can talk to, ask questions of, and build a relationship with for the years ahead.
Franca Adetunji
How it works
01
Pick a time that suits you. No paperwork, no pressure — just a conversation about what you are protecting.
02
Franca shops the market and brings back the options that actually fit your budget, health and goals.
03
Apply, get underwritten, and know exactly what your family receives and when.
Join our team
We are licensing and training independent financial professionals — no experience required, and remote work available across states.
Requirements: 18+, clean background, valid work permit or SSN, and residing in the US.
A 30-minute conversation costs you nothing and tells you exactly where you stand.